When Saudi Arabia reopened cinemas in 2018, the immediate economic story was exhibition: screens, ticket sales and new consumer spending. Eight years later, that phase is no longer enough to define the sector. The more important question is whether the Kingdom can turn a rapidly created box-office market into a durable film industry — one that develops intellectual property, employs skilled crews, attracts private capital and exports productions rather than merely importing films.
A market has been built
The consumer base is now substantial. According to Saudi Film Commission data reported by Argaam, cinemas generated SAR920.8 million in revenue from 18.8 million tickets in 2025, up 9% and 7% respectively from 2024. Saudi films earned SAR122.6 million from only 11 releases, giving local titles a disproportionately large share of revenue relative to the number of films screened.
Yet the exhibition market is also showing signs of maturity. The number of cinemas fell from 64 in 2024 to 62 in 2025, while screens declined from 630 to 603. That does not necessarily signal weakness; it may indicate consolidation after an unusually fast build-out. The key question is whether operators can raise attendance and profitability without relying on continued geographic expansion.
From demand to production capacity
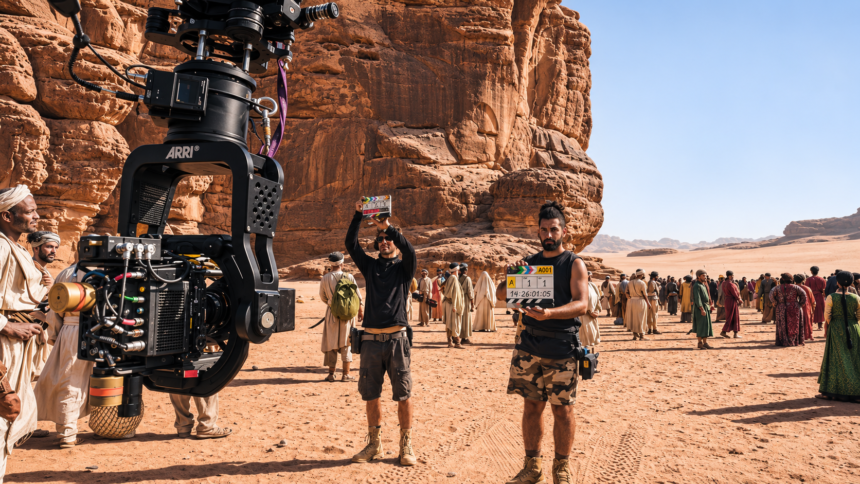
Government policy is increasingly focused on the supply side. The Film Commission’s industry data for 2024 counted 17 studios, 37 sound-isolated stages and 65 production companies. JAX Film Studios in Riyadh has since added an advanced virtual-production platform developed with Sony and Pixomondo, while AlUla and NEOM provide additional studio complexes and location-based production capacity.
The policy logic is clear: Saudi Arabia wants to capture more of the value chain — pre-production, shooting, post-production, visual effects, distribution and financing — instead of allowing most spending associated with local demand to flow abroad. In May 2026, the Film Commission raised its cash rebate to as much as 60% of eligible production expenditure, a highly competitive incentive designed to attract international projects and deepen local supplier networks.
But infrastructure alone does not create an industry. Studios must maintain high utilization, producers need predictable pipelines, and local companies must progress from service providers to owners of commercially valuable content. Otherwise, expensive facilities risk becoming showcases rather than productive assets.
Jobs and private capital
The strongest economic case for film lies in its spillovers. An impact analysis cited by the Film Commission found that incentive programs generated an average of about 1,230 jobs a year between 2020 and 2024, while every five production jobs were associated with two additional jobs in related industries. More than 2,500 crew members participated in media projects in 2024.
Financing is also becoming more sophisticated. The Cultural Development Fund has supported film companies through dedicated financing programs, while a SAR375 million private film fund announced in 2025 is intended to invest across production, distribution and infrastructure. At Cannes in 2026, officials said the Riviera Content Fund had already invested more than SAR54 million.
The real test, however, is whether private capital eventually accepts film risk without requiring the state to absorb much of it. Film is volatile: box-office success is unpredictable, export markets are competitive and production incentives can trigger subsidy competition between jurisdictions. Saudi policy will therefore need to distinguish between temporary market-building support and permanent dependence.
The export question
International expansion is the next frontier. Saudi participation at Cannes and other festivals gives producers access to co-production partners, distributors and investors; the Film Commission said it participated in 16 regional and international festivals during 2025. Combined with production rebates and new studios, this creates a platform for attracting foreign shoots and building cross-border industry relationships.
But hosting international productions is not the same as building globally competitive Saudi cinema. For that, local films must travel — commercially as well as culturally. The rise of Saudi titles at the domestic box office is encouraging because it proves that local stories can command audiences at home. The harder question is whether Saudi producers can develop genres, stars and intellectual property that work across the Arab world and eventually beyond it.
Saudi Arabia has already completed the first stage of its cinema experiment: creating a market almost from scratch. The second stage is more demanding. Success will depend less on how many screens or studios exist than on whether they remain busy, profitable and connected to a skilled domestic workforce. If private financing, local content and export distribution deepen together, cinema could become a genuine component of economic diversification. If not, the sector may remain impressive in scale but still dependent on policy support.