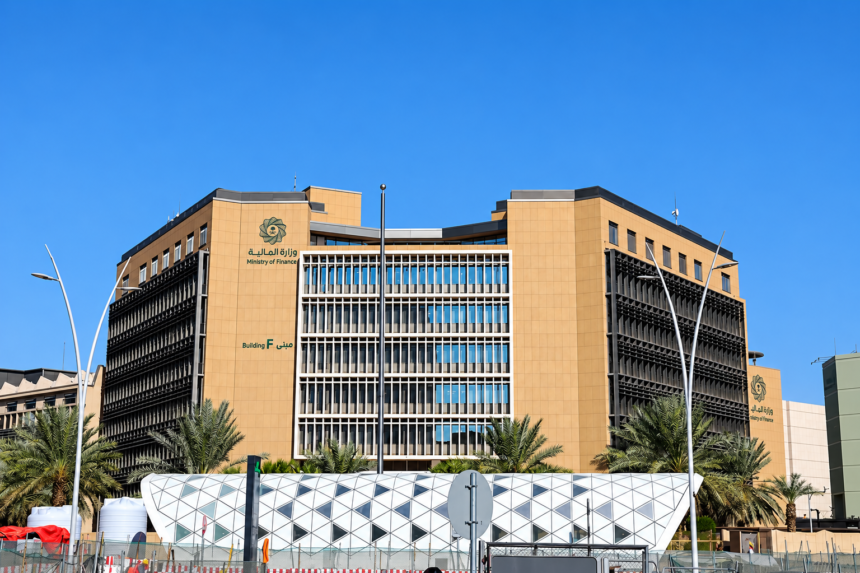
Saudi Arabia is borrowing more at a time when the economics of government debt are becoming less forgiving.
That does not mean the Kingdom faces a debt crisis. Its public debt remains moderate by international standards, and the IMF continues to assess Saudi debt as sustainable. But the combination of rising borrowing, persistent fiscal deficits and ambitious investment programmes raises a more interesting question: how much fiscal space should Saudi Arabia commit today in order to build the economic capacity it expects to need tomorrow?
The question matters because the global debt environment has changed. According to the IMF’s 2025 Global Debt Monitor, combined public and private debt reached about $251 trillion in 2024, equivalent to slightly more than 235% of global GDP. Public debt alone stood at $99.2 trillion.
The IMF’s April 2026 Fiscal Monitor estimates that global government debt rose to almost 94% of GDP in 2025 and could reach 100% by 2029. More importantly, government interest payments have risen from around 2% to nearly 3% of global GDP in only four years as countries refinance maturing obligations at higher rates.
This is the environment in which Saudi fiscal policy now operates.
Saudi debt is rising, but from a relatively low base
The IMF estimates Saudi public debt at 31.8% of GDP in 2025, rising to 32.1% in 2026 and 34.4% in 2027. Under its medium-term projections, government debt could reach about 44% of GDP by 2031.
Those figures remain far below the global public-debt ratio. The IMF also assesses Saudi debt as sustainable and the overall risk of sovereign stress as low, citing the Kingdom’s substantial financial assets among its important buffers.
But the direction of travel still matters.
Saudi Arabia’s National Debt Management Center estimates government financing needs at about SAR217 billion in 2026. Of that amount, SAR165 billion is intended to cover the projected budget deficit and approximately SAR52 billion to repay principal falling due during the year. The government had already prefunded around SAR61 billion of those requirements during 2025.
This illustrates the central problem of modern debt management. Borrowing is not only about financing new expenditure. Governments must increasingly manage old obligations while deciding how much new debt future budgets can comfortably absorb.
The Vision 2030 calculation
Saudi Arabia’s case is particularly important because rising borrowing is occurring alongside an unusually large economic transformation programme.
The Kingdom’s 2027 Pre-Budget Statement projects spending of around SAR1.392 trillion against revenue of SAR1.202 trillion, producing a deficit estimated at about 3.6% of GDP. The government plans to continue domestic and international financing while maintaining expenditure on development and strategic priorities.
The argument for this approach is straightforward: borrowing can be economically productive if it finances infrastructure and reforms that expand future growth and revenues.
There is already evidence of a changing revenue base. Saudi Arabia’s Ministry of Finance says non-oil revenues increased from approximately SAR166 billion in 2015 to SAR505 billion in 2025, while total government revenue is projected to rise from SAR1.202 trillion in 2027 to around SAR1.351 trillion by 2029.
The real test, therefore, is not whether Saudi Arabia borrows. It is whether additional borrowing creates enough future economic capacity to justify its cost.
Fiscal space is the real measure
This is where Saudi Arabia intersects with the wider global debt debate.
Debt-to-GDP ratios are useful, but they do not tell the whole story. Two countries with identical debt ratios can face very different risks depending on interest costs, maturity profiles, currencies, investor bases, financial assets and revenue capacity.
Saudi Arabia currently has significant advantages: comparatively moderate public debt, access to domestic and international capital markets and substantial financial buffers. But these advantages do not make the cost of capital irrelevant.
As borrowing accumulates, a growing share of future budgets must eventually be allocated to interest and principal repayments. The key policy question is whether government-financed investment raises productivity and non-oil revenues faster than those obligations constrain future fiscal choices.
Saudi Arabia therefore offers a useful example of the changing global debt debate. The challenge is no longer simply to keep debt low. It is to ensure that debt accumulated today builds enough economic capacity to pay for itself tomorrow.
In a world of costlier money, that distinction may become increasingly important to the success of Vision 2030.
Disclaimer: Views expressed by writers in this section are their own and do not necessarily reflect The Arabinform Journal point of view.
Indonesian economist, lecturer, business executive, and economic commentator. He teaches at STIES Mitra Karya Bekasi and has extensive experience in the private sector, including senior management roles at PT Tridharma Kencana Group. His areas of interest include macroeconomics, public policy, finance, trade, and business development. He is also an active contributor to Indonesian media, publishing articles on economic policy, financial markets, public debt, and broader economic developments.