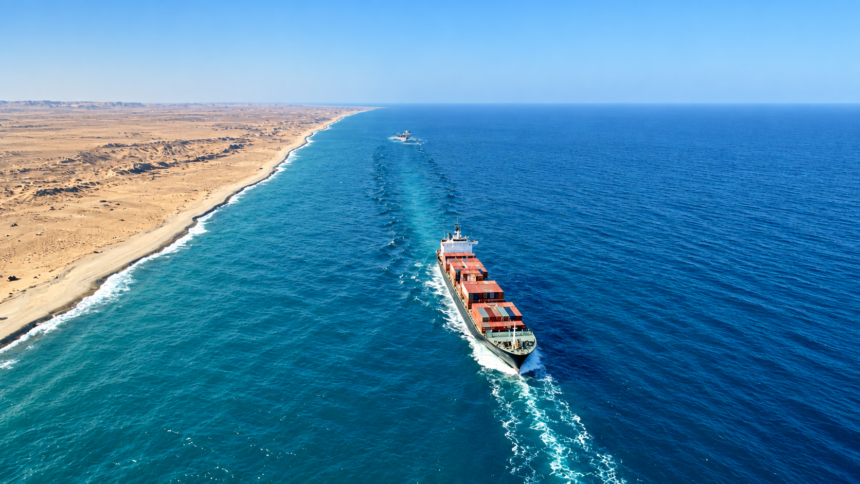
The Red Sea may appear distant from Pakistan’s immediate security environment, but instability there increasingly has consequences for the country’s economic and strategic interests in the Arabian Sea.
The two maritime spaces form part of an interconnected corridor linking the Indian Ocean and Gulf with the Bab el-Mandeb Strait, Suez Canal and European markets. Disruption at one chokepoint can quickly affect freight costs, energy flows, insurance premiums and shipping schedules elsewhere.
The scale of that vulnerability became clear after attacks on commercial shipping forced vessels away from the Red Sea and around the Cape of Good Hope. UN Trade and Development reported that by early May 2025, ship tonnage through the Suez Canal remained about 70% below the 2023 average, while longer routes were increasing fuel, insurance and operating costs.
The problem has not disappeared. Maritime tensions around both the Bab el-Mandeb and Strait of Hormuz have again intensified in 2026, reinforcing the broader lesson that Gulf, Red Sea and Arabian Sea security cannot easily be treated as separate strategic theatres.
Pakistan’s economic exposure
For Pakistan, the first vulnerability is trade.
Karachi Port and Port Qasim remain the country’s principal commercial maritime gateways, while Gwadar is being developed as a future connectivity and transshipment hub. Pakistan’s Planning Commission now places ports, shipping and regional connectivity at the centre of its broader Blue Economy strategy.
When vessels avoid Suez, journeys between Asia and Europe become longer. UNCTAD estimates that Red Sea rerouting can add roughly 12 days to an Asia-Europe voyage, increasing fuel use and reducing effective shipping capacity.
For Pakistani exporters operating on narrow margins, higher freight and insurance costs can weaken competitiveness. Importers face the same pressure on machinery, intermediate goods and consumer products, with some of those costs potentially feeding into domestic prices.
The country’s Middle Eastern trade exposure reinforces the point. Pakistan’s Ministry of Commerce reported bilateral trade with the Middle East of $18.77 billion in 2024–25, consisting of $3.21 billion in exports and $15.56 billion in imports.
Energy adds another layer. Disruptions affecting routes between the Gulf, Arabian Sea and Red Sea can influence not only shipping companies but also fuel costs, industrial production and the wider balance of payments.
Maritime security becomes economic security
Pakistan has already treated instability around commercial sea lanes as a security concern.
In January 2024, the Pakistan Navy deployed ships and increased aerial surveillance in the Arabian Sea following maritime-security incidents, saying the objective was to protect Pakistan-bound and international merchant shipping. In July that year, PNS Yarmook was deployed on a Regional Maritime Security Patrol to protect vessels travelling to and from Pakistani ports.
The implication goes beyond naval operations. Piracy, terrorism, drone and missile attacks, smuggling and geopolitical confrontation can impose economic costs even when Pakistan itself is not directly attacked.
This raises a broader question: should maritime risk be treated primarily as a defence problem, or as part of national economic planning?
Gwadar: opportunity, but not automatically
Regional disruption can also create opportunities for Pakistan’s ports.
A 2026 Pakistan Institute of Development Economics brief found that broader regional supply-chain disruption produced a temporary increase in activity at Pakistani ports. Port Qasim recorded an 8.2% increase in cargo throughput during July–March 2026, while Gwadar handled 11,000 containers in April alone, compared with 8,300 during all of 2025.
But PIDE’s more important conclusion was that geography is not enough. Shipping lines make long-term decisions on efficiency, transparency, costs, reliability and hinterland connectivity, not simply proximity to a crisis. A separate 2026 PIDE assessment similarly warned that temporary geopolitical diversion will not establish Gwadar as a lasting transshipment hub unless it becomes commercially competitive.
That distinction is crucial. Red Sea or Gulf instability may create a window for Pakistan, but port governance, customs procedures, road and rail links, digitalisation and regulatory predictability will determine whether temporary traffic becomes permanent business.
A wider maritime strategy
The emerging policy challenge therefore connects several areas that are often handled separately: naval security, ports, commerce, energy and diplomacy.
Pakistan’s planning authorities are already pursuing Gwadar operationalisation and closer maritime connectivity with the Gulf, including proposed transshipment links with Persian Gulf ports. The strategic question is whether these initiatives can be integrated with stronger maritime-domain awareness, more efficient ports and greater supply-chain resilience.
Cooperation with Saudi Arabia, the UAE, Oman and Qatar could also acquire greater importance because these states share interests in energy flows, ports, logistics and freedom of navigation.
The Red Sea and Arabian Sea are therefore increasingly part of the same economic-security equation. Pakistan cannot control instability around Yemen, Bab el-Mandeb or the Gulf. What it can influence is how exposed its own economy is to those disruptions.
Pakistan’s geography creates strategic relevance. Whether that geography becomes lasting economic advantage will depend less on crisis itself than on the efficiency, resilience and competitiveness of the maritime system Pakistan builds around it.
Disclaimer: Views expressed by writers in this section are their own and do not necessarily reflect The Arabinform Journal point of view.
A policy analyst and independent researcher based in Islamabad, Pakistan. He has been associated with the Centre for Pakistan and Gulf Studies (CPGS). His research interests include foreign policy, strategic affairs, security, and geopolitical issues.